Understanding how to get preapproved for mortgage finance in the UAE starts with three checks: lender eligibility, affordable repayments, and available purchase funds.
Pre-approval indicates your potential borrowing range. It remains conditional on the lender’s final financial checks, property assessment, and valuation.
Quick Answer: Compare suitable lenders, submit your identity and income documents, disclose existing debts and show evidence of your deposit. For a first home worth up to AED 5 million, expatriates need at least 20% of the price from their own funds (15% for UAE nationals), and total monthly debt repayments generally cannot exceed 50% of income. Pre-approval is conditional: check its expiry date, fees and outstanding requirements, and confirm the property qualifies for financing before committing.
What Is Mortgage Pre-Approval in the UAE?
Mortgage pre-approval is a lender’s conditional indication of how much you may be able to borrow. Banks may call it an Approval in Principle or initial approval, but terminology and assessment requirements vary.
| Stage | What it tells you | What remains |
| Eligibility estimate | Indicative borrowing range based on supplied details | Document verification and lender assessment |
| Pre-approval | Conditional borrowing eligibility | Outstanding financial checks and property assessment |
| Final approval | Approval for a specific property transaction | Offer acceptance, remaining conditions and completion |
Confirm what the lender has verified before relying on the amount shown. A mortgage calculator provides an estimate; a reviewed application carries more weight when planning your purchase.
Who Can Qualify for Mortgage Pre-Approval?
If you are researching how to get a mortgage in Dubai, check lender eligibility before comparing rates. Confirm that the bank accepts your income, employment, and residency status.
1. Income, Employment and Residency
Lenders assess:
- Documented income and its consistency.
- Employment or business trading history.
- Existing loans, credit cards and financial commitments.
- Credit history and repayment behaviour.
- Deposit funds and their source.
- Age, mortgage term and retirement income where relevant.
Minimum income, employment duration and age limits vary by lender and product.
2. Resident and Non-Resident Applications
Eligibility and financing limits differ for UAE nationals, expatriate residents and non-residents. Non-resident applicants should confirm accepted countries, income currencies and document requirements before applying.
For example, HSBC’s non-resident mortgage offers financing up to 60% of property value, subject to eligibility. This limit applies to that product, rather than all UAE mortgages.
How Much Can You Borrow, and What Deposit Is Required?
Your borrowing limit depends on repayment capacity and the financing permitted against the property. A larger deposit does not remove the need to demonstrate affordability.
1. How Your Debt Burden Ratio Affects Borrowing
Debt burden ratio, or DBR, compares monthly debt obligations with qualifying income.
Under the CBUAE mortgage framework, the standard debt burden ratio is 50% of gross salary and qualifying regular income. For beneficiaries of the Sheikh Zayed Housing Programme’s home finance, the CBUAE raised the limit to a maximum of 60%. Lenders must assess affordability and stress-test repayments, and individual eligibility depends on the applicable rules and lending criteria.
For example, AED 20,000 in qualifying monthly income gives a theoretical ceiling of AED 10,000 for all monthly debt obligations, including the proposed mortgage. Existing commitments reduce this capacity, and the lender may approve less.
2. Loan-to-Value Limits and Minimum Deposits
Loan-to-value, or LTV, expresses the mortgage amount as a percentage of the property’s assessed value.
For an eligible first owner-occupied home valued at AED 5 million or less, the 2020 CBUAE amendment sets these limits:
| Borrower category | Maximum LTV | Minimum contribution towards the price |
| UAE national | 85% | 15% |
| Expatriate | 80% | 20% |
These regulatory ceilings do not guarantee financing. Banks may require a larger contribution, and different purchase categories have different limits.
For an AED 1 million purchase financed at 80% of the price, you need AED 200,000 before fees, assuming the lender’s valuation supports that amount. Under CBUAE down-payment requirements, the deposit must come from your own resources, rather than personal loans or credit cards.
Under the Central Bank of the UAE’s mortgage regulations, the maximum financing amount is capped at seven times annual income for expatriates and eight times annual income for UAE nationals. The maximum mortgage term is 25 years. These are regulatory limits, not guaranteed borrowing amounts. Actual approval depends on the lender’s affordability assessment, debt burden ratio, loan-to-value limits and eligibility requirements.
Documents Required for Mortgage Pre-Approval
Request the lender’s checklist for your application stage. Initial assessments may require fewer documents than a fully reviewed pre-approval or final application.
1. Salaried Applicants
Prepare:
- Valid passport and Emirates ID where applicable.
- Residency documentation where applicable.
- Salary certificate meeting the bank’s requirements.
- Requested payslips and personal bank statements.
- Details of loans, credit cards and other liabilities.
- Evidence of savings and the deposit’s source.
Confirm the required statement periods and explain discrepancies between your salary certificate and bank credits. List commissions, bonuses and allowances separately, and ask which income components the lender accepts.
2. Self-Employed Applicants
Business owners may need:
| Document | Assessment purpose |
| Trade licence | Business activity and operating status |
| Ownership documents and memorandum of association | Shareholding and company structure |
| Business and personal bank statements | Cash flow and income verification |
| Audited financial statements | Business performance |
| Existing borrowing details | Outstanding commitments |
Distinguish company turnover from the personal income available for mortgage repayments.
Emirates NBD’s document guidance lists two years of audited reports for self-employed applicants. Requirements vary by lender and application stage.
3. Non-Residents and Joint Applicants
Non-residents should confirm requirements for overseas address, employment, and income evidence, including any translation or certification.
For joint applications, check whose income qualifies and which documents each borrower must submit.
Step by Step: How to Get Preapproved for Mortgage Finance
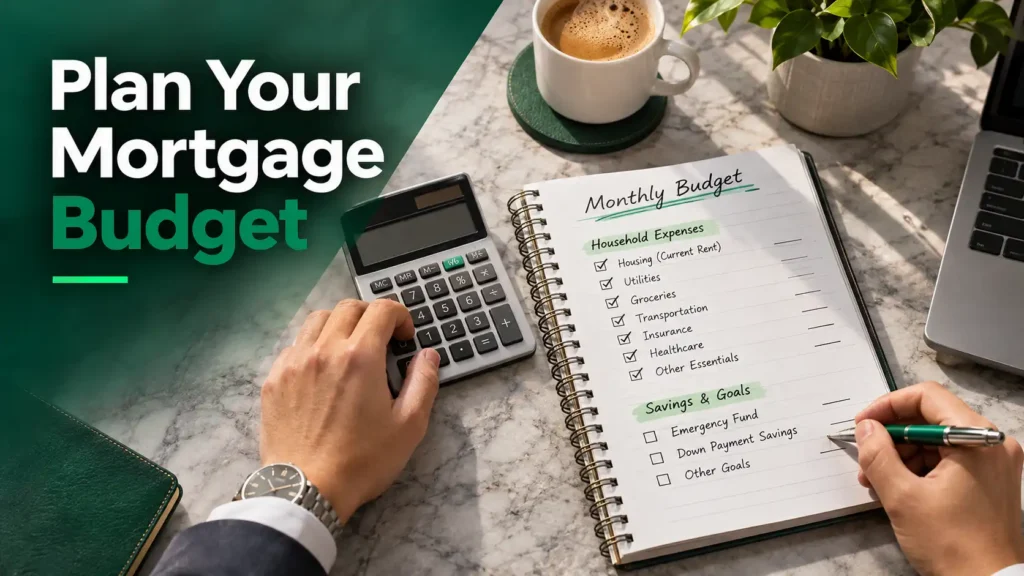
1. Set an Affordable Budget
Calculate what remains after essential spending, existing debts, and regular savings. Include service charges, maintenance, insurance, utilities, and annual expenses such as school fees. If you are choosing an apartment in Dubai, compare building costs and condition alongside the purchase price.
Keep emergency savings separate from purchase funds. Test whether you could manage higher repayments after an introductory fixed-rate period ends, rather than relying on the bank’s maximum approval.
2. Review Your Credit Information
Check your credit report through the Al Etihad Credit Bureau (AECB), the UAE’s official credit bureau. Review account details, balances, and repayment records, and request correction of inaccurate data from the reporting financial institution before applying.
Ask how the lender assesses credit-card limits and existing loans. A zero card balance may not remove its effect on your borrowing capacity.
3. Compare Suitable Lenders
Shortlist lenders that accept your residency, employment type, income source, and intended purchase. Compare offers using the same loan amount and term.
| Comparison point | Question to ask |
| Introductory rate | How long does it apply? |
| Subsequent rate | What benchmark, margin, and reset frequency apply? |
| Fees | Which bank, valuation, and broker charges are payable? |
| Conditions | Is salary transfer or a particular account required? |
| Repayment flexibility | What charges or limits apply to overpayments and early settlement? |
Request each lender’s Key Facts Statement (KFS) to review the mortgage’s interest or profit rate, applicable fees, repayment terms and key risks. The CBUAE requires licensed financial institutions to provide this document before supplying a financial product or upon the consumer’s request.
Request a repayment illustration showing initial payments and potential changes. For rates linked to EIBOR, the UAE dirham interbank benchmark used in lending, confirm the benchmark period, bank margin, and any minimum rate.
Compare total costs over your expected borrowing period. Where relevant, assess conventional mortgages and Islamic home finance using their payment structures and contractual terms.
4. Submit Complete and Consistent Documents
Use the bank’s approved application channel. Check that name, employment details, and declared commitments match your supporting documents.
Explain unusual deposits, variable earnings or recent changes when requested. Submit sensitive documents through verified channels, retain copies and track outstanding requests.
5. Confirm Credit Checks and Fees
Before authorising an application, confirm:
- Which credit checks the lender will conduct.
- When fees become payable.
- Whether charges are refundable if you do not proceed.
Compare preliminary quotations before submitting multiple applications. Do not assume overseas rules for grouping mortgage credit inquiries apply in the UAE.
6. Review Your Conditional Approval
Review the letter using the checklist below, then set a property budget that includes your deposit and purchase costs. Use that budget to shortlist properties for sale in the UAE, and confirm each property’s financing eligibility with your lender.
How Long Does Mortgage Pre-Approval Take?
Processing time depends on the lender, assessment requirements, and completeness of your documents. The approval’s validity period is separate from the time needed to obtain it.
HSBC’s application guidance states that its Approval in Principle usually takes around 60 minutes after the requested documents are submitted and remains valid for 60 days. These timings apply to HSBC’s initial assessment, not the full mortgage process.
| Stage | What can affect timing? |
| Document preparation | Obtaining certificates, statements and business records |
| Pre-approval assessment | Financial verification and requests for clarification |
| Final property approval | Valuation arrangements and property eligibility |
| Purchase completion | Outstanding conditions and registration requirements |
Confirm when the lender’s processing period starts. Missing documents or requests for clarification can delay the decision.
Apply when you are ready to begin a focused property search. If your approval expires, the lender may require updated documents and reassessment before renewing it.
Mortgage Pre-Approval Costs and Dubai Purchase Fees
Budget separately for pre-approval charges and purchase expenses. A free initial assessment does not cover the costs of arranging the mortgage or completing the transaction.
1. How Much Does Mortgage Pre-Approval Cost?
HSBC describes its Approval in Principle as free. Charges elsewhere depend on the lender, broker and service.
Confirm in writing:
- Application or assessment fees.
- Broker charges and when they become payable.
- Refund terms if you do not proceed.
- Separate mortgage processing fees.
2. Additional Mortgage and Property Purchase Costs
| Expense | What to confirm |
| Bank arrangement fee | Current charge and applicable VAT |
| Property valuation | Fee and payment deadline |
| Sale registration | Relevant emirate’s fee and who pays |
| Mortgage registration | Applicable rate and additional charges |
| Transaction services | Trustee and administration fees |
| Insurance | Required life and property cover |
| Agency or developer charges | Contractual fees and payment terms |
DLD mortgage registration costs 0.25% of the mortgage value, plus additional applicable charges. These figures apply to Dubai, not automatically to other emirates.
3. Example: Cash Required for an AED 1 Million Purchase
Dubai’s sale registration fee is 4% of the property value, normally divided equally between buyer and seller unless agreed otherwise. The following example assumes an AED 800,000 mortgage and an agreement requiring the buyer to cover the full 4% registration fee:
| Item | Amount |
| Contribution towards purchase price | AED 200,000 |
| Sale registration at 4% | AED 40,000 |
| Mortgage registration at 0.25% | AED 2,000 |
| Subtotal | AED 242,000 |
This subtotal excludes bank fees, valuation, transaction services, insurance, and other applicable expenses.
Request a complete cost breakdown and payment schedule before committing. Confirm what is due at application, valuation, contract signing, and transfer, including any upfront fees later refunded or offset.
Explore more property listings and real estate guides on Shozon
What Should You Check in Your Pre-Approval Letter?
Review the document against this checklist:
- Maximum conditional loan amount.
- Expiry date and renewal process.
- Deposit and income assumptions.
- Outstanding documents or verification.
- Permitted property categories or restrictions.
- Any quoted pricing and its conditions.
- Requirements for final approval.
Do not assume a quoted rate is locked simply because a borrowing amount is approved. Request explicit confirmation of any rate reservation, its expiry, and its conditions.
Ask how a job change, new borrowing, or reduced income would affect the decision. Keep the lender informed of material changes before completion.
What Happens After Pre-Approval?
For buyers learning how to buy property in Dubai, the next step is confirming that the lender accepts the chosen property and that the purchase can meet its financing and completion requirements.
If you are considering an apartment, browse apartments for sale in UAE and compare suitable listings against your budget.
1. Confirm the Property Is Eligible
Check the development, building, and ownership arrangement with your lender. Confirm whether financing is available for a completed home, a property under construction, or a payment due at handover.
Compare off-plan and ready properties to understand how payment schedules, delivery risks, and inspection options differ.
Overseas buyers should also confirm:
- Document-signing requirements and whether attendance is necessary.
- Fund transfer arrangements and currency conversion.
- Payment deadlines and responsibilities at completion.
A developer payment plan does not guarantee mortgage eligibility. Obtain property-specific confirmation before relying on financing for a future payment.
2. Budget for a Lower Property Valuation
The lender’s valuation may be lower than the agreed price. Understanding property valuation in Dubai helps you assess how this difference could affect your required contribution. This hypothetical example assumes financing at 80% of the bank’s valuation:
| Item | Amount |
| Agreed purchase price | AED 1,000,000 |
| Bank valuation | AED 950,000 |
| Mortgage at 80% of valuation | AED 760,000 |
| Buyer contribution towards the price | AED 240,000 |
Compared with an anticipated AED 800,000 mortgage, the buyer needs an additional AED 40,000 before fees.
3. Meet the Final Approval and Completion Requirements
Review the final mortgage offer, outstanding conditions, insurance requirements, and payment arrangements.
Before signing a purchase agreement or paying a deposit, check the financing clauses, valuation provisions, deadlines, and consequences if the purchase cannot proceed.
Why Can Approval Be Delayed or Declined?
Common obstacles include incomplete evidence, unverifiable income, inconsistent declarations, credit issues, new commitments, and an unacceptable property.
If the lender raises concerns:
- Request the specific reason and outstanding requirements.
- Correct factual errors and provide missing evidence.
- Reassess the price range or deposit where necessary.
- Confirm whether another application would address the actual issue.
Changing banks does not resolve an unaffordable purchase. Avoid making further commitments until you understand the financing gap.
Prepare Your Finances Before Committing
Knowing how to get preapproved for mortgage finance means checking eligibility, organising evidence, and budgeting beyond the deposit.
Use the conditional decision to guide your search, then confirm the property, final lending terms, and complete cash requirement before committing to a purchase.
Frequently Asked Questions
What is the best way to get a mortgage pre-approval?
Compare eligible UAE lenders, prepare complete financial documents, disclose existing debts, and review the conditions before relying on the approved amount.
What are the requirements to qualify for a pre-approval mortgage?
Lenders assess documented income, employment or business history, credit records, existing debts, deposit funds, and eligibility under their lending criteria.
How far in advance should I get pre-approved for a mortgage?
Apply before serious property hunting, allowing time for assessment and checking that the letter’s validity covers your expected search period.
Is there a downside to getting pre-approved for a mortgage?
Potential drawbacks include application fees, credit checks depending on the lender’s process, and needing reassessment if the approval expires.
What disqualifies you from a mortgage?
Insufficient qualifying income, excessive debts, serious credit issues, unverifiable information, or an ineligible property can lead to rejection.
Is it common to be denied a mortgage after pre-approval?
There is no reliable UAE-wide rate, but rejection remains possible if finances change, conditions are unmet, or the property fails assessment.
Is preapproval the same as approval?
No. Preapproval indicates conditional borrowing eligibility; final approval requires satisfactory financial verification, property assessment and fulfilment of the lender’s conditions.
What documents are needed for mortgage preapproval?
Typically, identity documents, income evidence, bank statements, liability details and deposit evidence are requested, with additional business records for self-employed applicants.
How much will I get pre-approved for?
Your amount depends on qualifying income, existing commitments, affordability checks, deposit funds, and applicable financing limits, subject to the lender’s assessment.
Is it better to be preapproved or prequalified?
A reviewed preapproval generally provides a firmer borrowing indication than an initial estimate, but confirm what the lender has verified because terminology varies.
How much down payment do I need for a mortgage in the UAE?
For a first home worth up to AED 5 million, expatriates need at least 20% of the price and UAE nationals at least 15%, paid from their own funds rather than loans. Purchase fees are additional.
How long is mortgage pre-approval valid in the UAE?
Validity depends on the lender. HSBC, for example, states that its Approval in Principle is valid for 60 days, so check the expiry date on your letter before starting your property search.
Sources
- Central Bank of the UAE: Regulations Regarding Mortgage Loans
- Central Bank of the UAE: 2020 Mortgage Loan Amendments
- Central Bank of the UAE: Consolidated Mortgage Regulations
- Central Bank of the UAE: Protection of Consumer Data and Assets
- Central Bank of the UAE: EIBOR Rates
- Dubai Land Department: Know Your Rights for Real Estate Investors
- Dubai Land Department: Mortgage Registration
- Emirates NBD: Home Loan Application and Documents
- HSBC UAE: Non-Resident Mortgages
- HSBC UAE: Mortgage Application Requirements
- HSBC UAE: Approval in Principle