Dubai developers often advertise off-plan units with 1% monthly payment plans. The headline figure looks small, but it describes only one part of the payment schedule. This guide explains how these plans work, shows what an AED 1 million unit would cost in practice, and lists what to check in the SPA before you pay a booking amount.
Before booking, check whether you can fund every payment when it falls due, particularly the largest one. The figures below are illustrative; the selected unit’s sale and purchase agreement (SPA) sets out its actual amounts and dates.
How Does a 1% Payment Plan in Dubai Work?
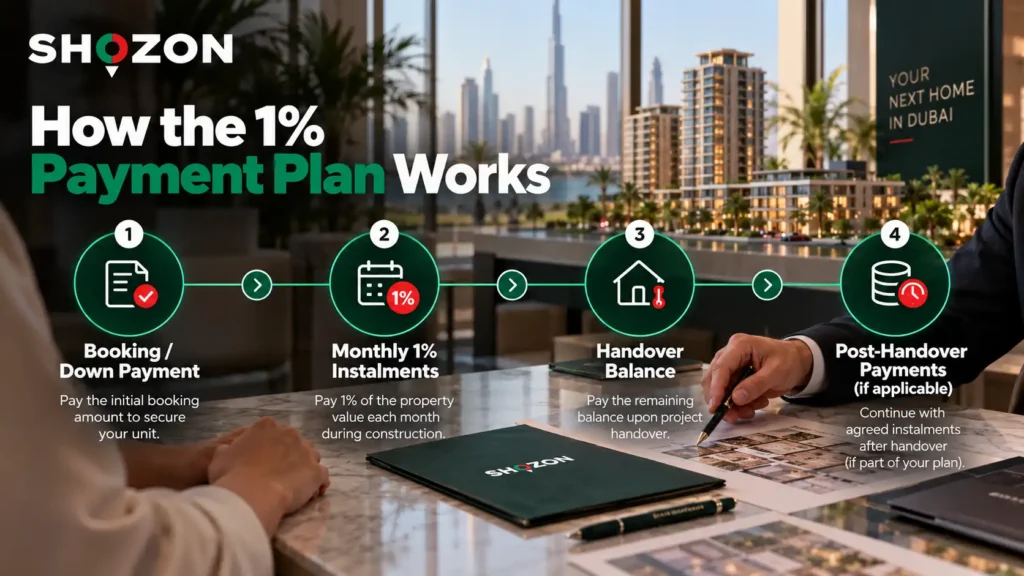
A 1% payment plan usually means the buyer pays monthly instalments equal to 1% of the property price. It does not mean the total upfront payment is only 1%. Buyers may also need to pay a booking amount, down payment, registration fees, milestone payments, and a balance at handover.
- Monthly instalment = usually 1% of the purchase price
- Additional upfront and milestone payments may apply
- A significant balance may still remain at handover
1% Payment Plan Dubai: What Does the 1% Actually Mean?
A 1% monthly instalment is usually calculated from the agreed property price. On an AED 1 million apartment, that would be AED 10,000 for each scheduled monthly payment.
The 1% figure does not show how the rest of the price is payable.
| What “1% monthly” tells you | What you still need to confirm |
| The amount of a scheduled monthly instalment | The booking amount and down payment |
| The size of recurring payments | How many are due and whether other instalments apply |
| Part of the purchase price is paid over time | The balance due at handover |
| Payments may be spread across several stages | Whether any continue after handover and what charges sit outside the price |
The booking amount, down payment and monthly instalment are separate terms. A booking amount may count towards the down payment; confirm this in writing before paying.
When evaluating a 1 percent payment plan Dubai property advertisement, check the full price, number of monthly payments, additional amounts and final balance. Two offers with the same 1% monthly instalment can require very different amounts upfront and at handover.
How Do 1% Instalments Fit into the Full Payment Schedule?
A 1% offer applies to a specific property and unit. Request a dated payment schedule before judging affordability, since the monthly figure does not show when the full price is due.
1. Booking and Initial Payment
Check whether the booking amount is refundable, when the sale and purchase agreement (SPA) must be signed, and whether the booking amount counts towards the down payment.
For example, “20% down” may include the booking payment rather than require it on top of the 20%. Confirm the amounts in writing.
2. Monthly Instalments
Check when the 1% payments begin and end, then count them. Forty-eight instalments of 1% equal 48% of the purchase price. The schedule must account for the remaining 52%.
Find out whether payments fall on fixed dates and whether larger, construction-linked instalments are also required.
3. Additional Payments and Handover
Identify the amount due at each construction milestone and at handover. For every payment, check its amount, due date or trigger, and what the SPA says if the expected handover date changes.
4. Payments After Handover
Some plans continue after handover; others require the outstanding balance before the buyer receives the property. Confirm which applies to the selected unit.
The wider off-plan purchase process in Dubai includes registration and handover. For this payment decision, use the unit’s own dated schedule.
What Would a 1% Plan Cost on an AED 1 Million Property?
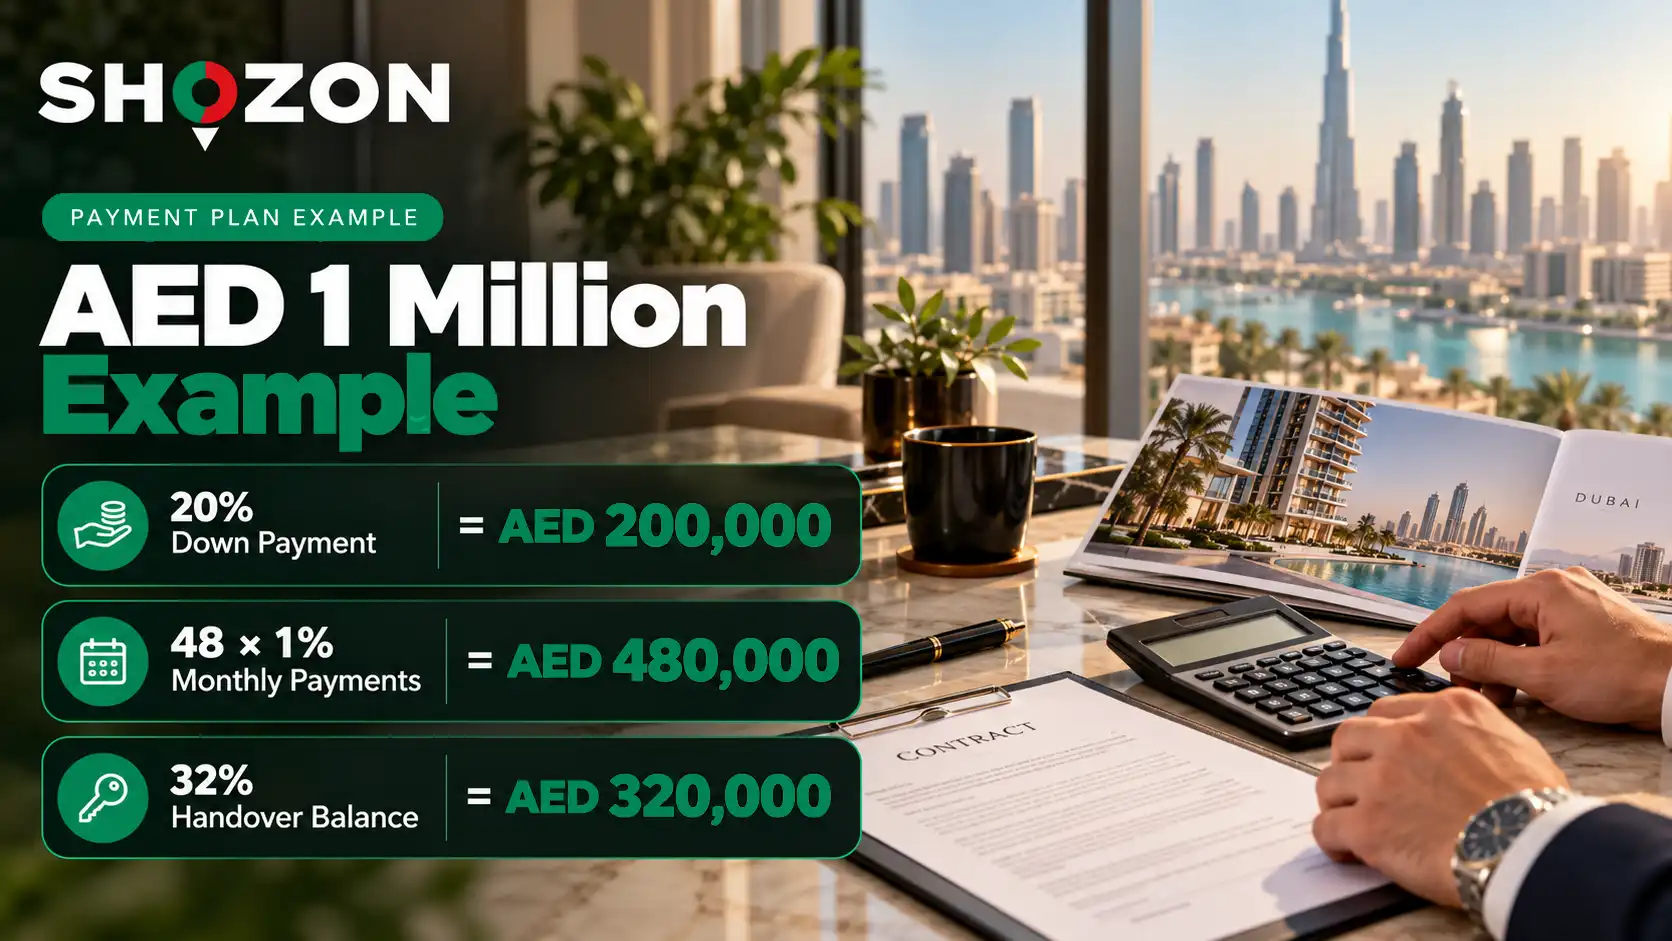
Consider an illustrative AED 1 million purchase with a 20% down payment, forty-eight monthly instalments of 1%, and the remaining balance due at handover. This is a calculation example, not an offer for a current development.
| Payment stage | Calculation | Amount |
| Initial down payment | 20% × AED 1,000,000 | AED 200,000 |
| Each monthly instalment | 1% × AED 1,000,000 | AED 10,000 |
| Total of 48 monthly instalments | 48 × AED 10,000 | AED 480,000 |
| Balance at handover | 32% × AED 1,000,000 | AED 320,000 |
| Total property price | 20% + 48% + 32% | AED 1,000,000 |
The AED 10,000 monthly payment is only one part of the schedule. The buyer also needs AED 200,000 initially and AED 320,000 at handover. Applicable transaction charges must be budgeted separately unless the written offer specifies that the developer will cover them.
Look at Cumulative Payments, Not Just the Monthly Amount
The same example shows how much of the AED 1 million price remains unpaid at each stage:
| Point in the schedule | Price paid to date | Price still outstanding |
| After the 20% down payment | AED 200,000 | AED 800,000 |
| After 12 monthly instalments | AED 320,000 | AED 680,000 |
| After 24 monthly instalments | AED 440,000 | AED 560,000 |
| After 48 monthly instalments | AED 680,000 | AED 320,000 |
| After the handover payment | AED 1,000,000 | AED 0 |
The key figure is AED 320,000 still due after all 48 monthly instalments. The table tracks payments towards the property price; it does not include registration or other transaction charges.
A Second 1% Offer Can Require More at Handover
Consider another illustrative AED 1 million unit with 10% due initially, thirty monthly payments of 1%, and the remaining 60% due at handover.
| Payment stage | Share of price | Amount |
| Initial payment | 10% | AED 100,000 |
| Thirty monthly instalments | 30% | AED 300,000 |
| Handover balance | 60% | AED 600,000 |
| Total property price | 100% | AED 1,000,000 |
Both examples have an AED 10,000 monthly instalment. This offer requires AED 100,000 less initially, but AED 280,000 more at handover. That difference matters more than the shared “1% monthly” label when planning how to complete the purchase.
How Can You Test Whether the Payments Are Affordable?
Check three amounts separately: cash needed at the start, monthly commitments, and the largest future payment. Keep enough funds for living expenses and unexpected costs after each one.
1. Test the Monthly Commitment
Add the 1% instalment to payments that will continue during construction, including rent and existing debts. On the illustrative AED 1 million property, a buyer paying AED 10,000 monthly to the developer and AED 7,000 in rent has AED 17,000 in combined housing payments before other expenses.
The instalment is calculated from the property price, not the buyer’s income. Check whether it remains manageable if income falls for several months.
2. Fund the Handover Balance Before Booking
Identify how you would pay the AED 320,000 handover balance in the first example. Saving that amount evenly over 48 months would require about AED 6,667 a month, on top of the AED 10,000 contractual instalment. This is a budgeting calculation, not another payment charged by the developer.
If a mortgage is essential to your plan, discuss eligibility with a lender early. A possible future application does not guarantee approval or a particular loan amount at handover.
3. Test a Less Favourable Outcome
Check whether you could still meet the contractual payments if:
- Your income falls temporarily.
- The handover date changes.
- The approved mortgage is smaller than expected.
- The property takes longer to rent or sell.
- Ownership or fitting-out costs exceed your estimate.
A plan is more sustainable when its payments do not depend on an early resale, immediate rental income or the maximum possible mortgage.
What Costs Sit Outside the Advertised 1%?
The 1% instalment pays towards the property price. Budget separately for charges that apply to the purchase and for costs that begin at handover.
| Cost | What to confirm |
| DLD registration | The amount payable by each party and when it is due |
| Developer and brokerage charges | Whether they apply, who pays them and whether they are included in the quotation |
| Mortgage costs | Bank, valuation, insurance and registration charges if finance is used |
| Handover and utility costs | Amounts needed to take possession and prepare the unit |
| Service charges | The amount and the date from which the owner must pay |
Dubai Land Department’s initial sale registration service lists 2% of the sale value for the seller and 2% for the purchaser, along with other stated fees. Confirm the allocation agreed for your purchase. If the buyer pays the full 4% on an AED 1 million property, that adds AED 40,000 beyond the purchase price.
In the first example, the AED 200,000 down payment plus AED 40,000 in buyer-paid registration would require AED 240,000 if both are due at the outset. Request an itemised statement showing each charge and its payment date. The wider costs of buying property in Dubai may include other amounts depending on the transaction.
How Does a 1% Plan Compare with 80/20 and 60/40 Plans?
An 80/20 payment plan Dubai offer or 60/40 payment plan Dubai offer describes a division of the property price. It does not, by itself, tell you the payment dates. The examples below assume the first portion is paid before handover and the second at handover; an actual offer may define the stages differently.
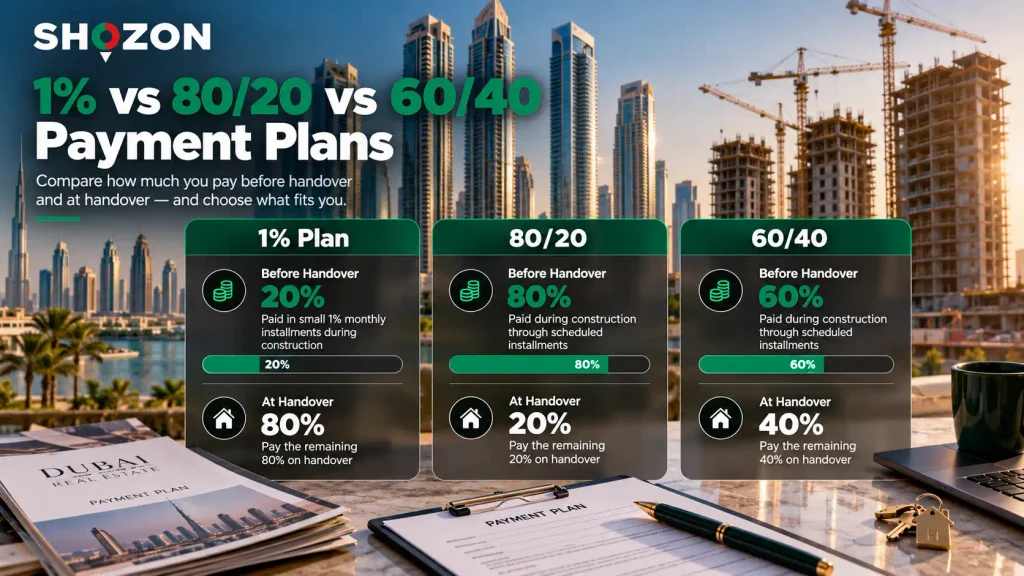
A “1% monthly” offer instead describes the size of recurring instalments. It may also require a down payment and a handover balance.
| Illustrative plan on an AED 1 million property | Paid before handover | Due at handover |
| 1% monthly: 20% down plus 48 monthly payments | AED 680,000 | AED 320,000 |
| 80/20: 80% before handover, 20% at handover | AED 800,000 | AED 200,000 |
| 60/40: 60% before handover, 40% at handover | AED 600,000 | AED 400,000 |
Each example totals AED 1 million before transaction charges. Compare the dated instalments and the largest payment, not the plan’s label: an 80/20 or 60/40 offer could distribute its first portion very differently from the 1% example. When comparing off-plan properties for sale, request the dated schedule for each shortlisted unit.
Do 1% Payments Continue After Handover?
A post-handover payment plan offered by a Dubai developer allows part of the purchase price to remain payable after handover.
For example, an illustrative AED 1 million plan could require 10% initially, 40% during construction and 10% at handover. The remaining 40% could then be paid through forty monthly instalments of AED 10,000. Another unit advertised with “1% monthly” might instead require its full outstanding balance at handover.
Before relying on post-handover payments, confirm:
- The balance due before you can take possession.
- The number, amount and dates of payments after handover.
- Any additional lump sums or charges.
- When service charges begin and what happens if a payment is late.
Rent may help an owner meet later instalments, but the unit might not be leased immediately. Check that the payments remain affordable without prompt rental income. Shozon’s off-plan investment guide covers the wider rental and resale decision.
Can a Mortgage Cover the Handover Balance?
A mortgage may help fund the amount due at handover, but the buyer must qualify for it, and the lender must accept the property. Approval, the property valuation, and the amount available cannot be assumed when signing a developer payment plan.
The UAE Central Bank’s mortgage rules cap the loan-to-value ratio at 50% for a property being purchased off-plan. If finance is assessed after completion, the applicable category may differ; the lender must still assess the buyer and property. Confirm the terms with a lender before relying on a mortgage to pay the handover balance.
Before booking, ask a lender what documents and conditions would apply to the planned financing. Budget for any gap between the handover balance and the amount ultimately approved, as well as mortgage-related charges.
What Are the Risks Specific to a 1% Payment Plan?
1. A Large Balance May Remain at Handover
In the first AED 1 million example, forty-eight payments of AED 10,000 still leave AED 320,000 due at handover. Identify how you will fund that amount before committing to the monthly schedule.
2. A Changed Handover Date Can Affect Your Budget
A later handover may extend the period in which you pay rent alongside property instalments. Check whether payments follow fixed dates or construction milestones, and read the SPA provisions covering changes to the expected completion date. Do not assume that payments automatically pause during a delay.
3. Missing an Instalment Has Consequences
Review the SPA’s payment, notice, termination, and refund terms. Dubai Land Department’s termination of initial registration procedure sets out a notice process for applicable off-plan payment defaults. The outcome depends on the contract and the applicable procedure; one missed instalment does not, by itself, establish that every amount paid will be lost.
4. A Planned Sale May Not Fund the Next Payment
If you expect to sell before handover, check for any developer approvals, payment thresholds, and transfer conditions in the SPA. Assess the rental and resale assumptions behind your plan, and keep a way to meet the next instalment if the property does not sell when expected.
What Should You Verify Before Paying a Booking Amount?
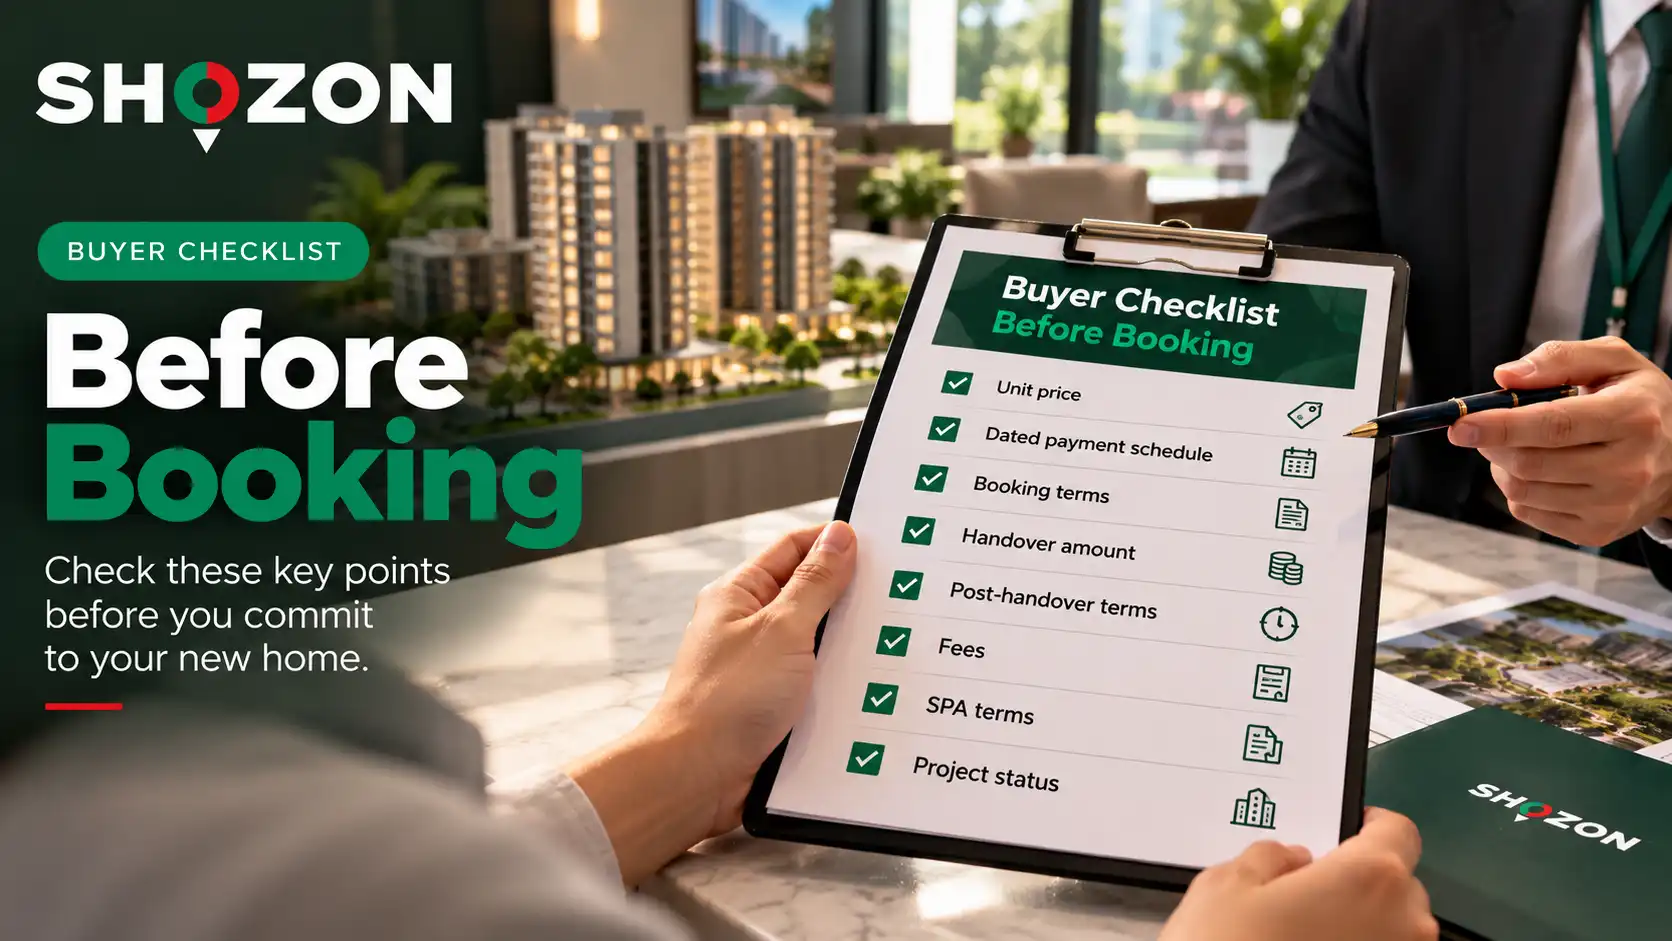
Request the terms for the selected unit, since a project advertisement may not show every payment or condition that applies to it.
| Ask for | What to confirm |
| Unit-specific price and dated schedule | The down payment, number of 1% instalments and total price payable |
| Booking terms | Whether the payment counts towards the down payment and when it may be refunded |
| Milestone and handover amounts | Every payment outside the monthly instalments |
| Post-handover schedule, if offered | The outstanding balance, payment dates and conditions for possession |
| Itemised charges | What must be paid in addition to the property price, and when |
| SPA terms | What happens if handover changes, a payment is missed or you need to sell |
| Project and payment details | Whether the project status and proposed payment instructions match official information |
Check the project through Dubai Land Department’s project-status enquiry, available on its website and Dubai REST. Then compare the payment instructions with the documents for the selected unit.
If the advertisement and unit-specific schedule differ, request a corrected schedule before paying the booking amount.
Who Might Find a 1% Plan Suitable?
A 1% plan may suit a buyer who can cover the initial payment and fees, make the monthly instalments alongside existing expenses, and fund any balance at handover. The property price and full schedule matter more than the advertised monthly percentage.
It may be unsuitable if the booking payment would exhaust the buyer’s savings, income is too uncertain to support the instalments, or the handover balance depends entirely on an unapproved mortgage or a quick resale. In that case, compare ready properties for sale in UAE, where the price and financing are settled at transfer rather than spread over a construction period.
The decision rests on whether every payment remains manageable when it falls due, while leaving room for ordinary expenses and a cash reserve.
Check the Full Payment Schedule Before You Book
Compare offers by the total price, cash required upfront, monthly instalments, and amount due at handover. If you cannot identify a reliable way to fund the largest payment, the advertised 1% monthly figure is not enough to establish that the property is affordable.
Explore more properties on Shozon
FAQs About 1% Payment Plans in Dubai
What is a 1% payment plan in Dubai?
It generally means scheduled monthly payments of 1% of the property price, in addition to any separate down payment, fees, and the remaining balance in the SPA.
Is a 1% monthly payment plan available in Dubai?
Yes, selected developers offer 1% monthly instalments, but availability and the complete terms depend on the project and unit.
Do 1% payments continue after handover?
Only if the selected unit’s SPA includes post-handover instalments. Otherwise, the remaining balance may be due at handover.
What happens if I miss a payment on a 1% plan?
Check the SPA for the payment deadline, notice process, and consequences of missed instalments. A missed payment does not automatically cancel every contract.
Which is the best payment plan?
The best plan is the one whose full price, dated payments, and largest future balance fit the buyer’s funds and the property’s value.
Can I get a mortgage in the UAE without a down payment?
Do not assume so; mortgage lending is subject to loan-to-value limits, lender approval, and the buyer’s own funding contribution.
Can you get a 100% mortgage in Dubai?
A buyer should not plan on a 100% mortgage, as applicable lending limits and lender assessments require a contribution from other funds.
Sources